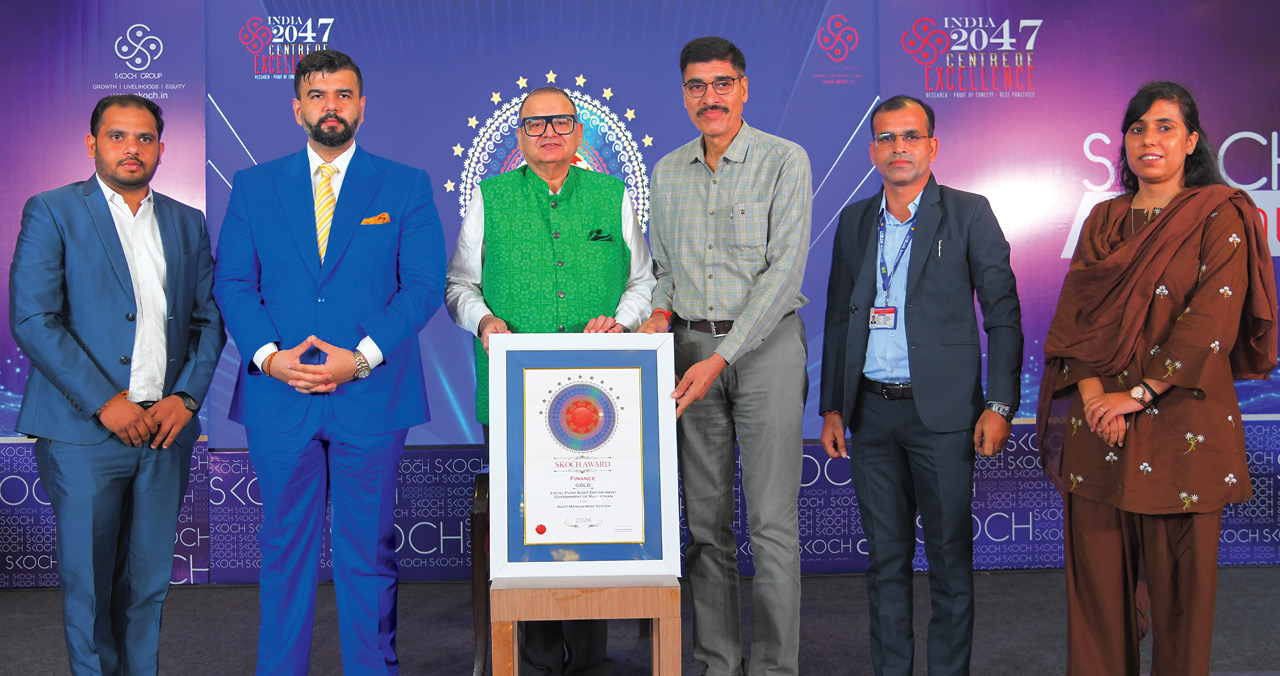
(L to R) Gaurav Gupta, Local Fund Audit Department, Government of Rajasthan; Rohan Kochhar, SKOCH Development Foundation and Founder, SKOCH Law Offices; Sameer Kochhar, Chairman, SKOCH Group; Apoorv Joshi, Director, Local Fund Audit Department; Om Prakash Sharma and Sunita Brar, Local Fund Audit Department
For years, auditing thousands of local bodies across Rajasthan began with something surprisingly basic: a lottery.
Audit units were selected manually, records were processed through an offline system, reports passed through multiple layers of approval and compliance was managed separately. The process worked but offered little ability to direct scarce audit capacity towards institutions or transactions with the greatest risk. As datasets grew, identifying suspicious transactions manually became even harder.
Rajasthan’s Local Fund Audit Department decided to overhaul the architecture. Its Audit Management System (AMS), launched in September 2021, has transformed local fund audit from a largely manual exercise into a digital, risk-based system that allocates audit capacity more effectively. The project sits within the Finance Department and covers an unusually diverse universe, ranging from Panchayati Raj Institutions and urban local bodies to development authorities, housing boards, universities and other institutions.
The transformation is evident in one number. Approved audit reports rose from 1,790 in 2021-22 to 9,992 in 2024-25. AMS generated 11,935 reports in 2025-26, against 12,373 active units. But the more important story is that AMS redirects audit capacity towards higher risk, rather than simply digitising the process.
AMS digitises the audit lifecycle, spanning planning, execution, reporting, compliance and monitoring. Rather than relying on the old lottery approach, it introduces two-tier risk profiling to target audit attention more precisely. At the first level, units are selected based on financial and non-financial risk parameters. At the second level, transactions themselves can be sampled for scrutiny. This shifts the fundamental question from which institution is audited to where audit attention is most needed.
The system integrates with platforms such as Raj-e-Panchayat, IFMS, and RajSSO, enabling electronic entry of transaction information into the audit process. Audit teams can be formed online, duties allocated, daily diaries maintained and reports routed through workflow-based approvals.
An audit memo can be converted into a para. Paras can be classified and standardised using templates. They receive system-generated numbers and cannot be deleted or omitted. Records are stored electronically and reports no longer need to be physically transported between offices. Serious embezzlements and Category ‘A’ paras can also be tracked centrally.
In other words, digitisation is doing more than eliminating paper. It is making audit attention more targeted and clarifying the central claim.
The scale presented for 2025-26 shows how deeply AMS has become embedded in routine operations.
The system had 10,534 active users, covered over 30 unit types and spanned all 33 districts, as shown on the implementation dashboard. It recorded 12,163 audit plans and 117 audit parties. Of planned audits, 98.71% had started and 97.01% of audit-related reports had been approved.
AMS generated 157,416 memos, of which 156,394 (99.71%) were converted into audit paras. More than 600 staff had been trained, with training ongoing.
The broader cumulative implementation picture is equally striking: 54,069 audit plans, 38,401 audits started, 37,966 reports approved and 460,907 paras created. The system covered all 41 districts shown in the later dashboard and more than 1,000 staff were trained through repeated and refresher programmes.
These numbers matter because government auditing is ultimately a problem of scale and direction. They also show why the transition to a digital system matters. It makes thousands of simultaneous audit processes visible, manageable and more targeted.
The transition was not automatic. Field auditors accustomed to traditional methods had to shift to a fully digital platform. Data had to be exchanged across external IT systems. Remote Gram Panchayats posed connectivity and compliance challenges. The sheer volume of transactions complicated risk-based sampling.
That experience taught an important lesson: digital transformation requires continuous handholding, not just software installation. The department identifies staff capacity building and the quality and interoperability of external data as critical to effective risk-based auditing.
The design consequently extends beyond auditors. Audit units themselves can access memos and para lists, manage audit fees, submit compliance, raise grievances and work with documents online. Audit parties, meanwhile, can manage transactions, materiality, audit areas, work allocation, memos, paras, daily diaries and reports within the same environment. This creates a common digital space between auditor and auditee, which matters for both transparency and follow-up. It also prepares the ground for the next phase.
The next phase, AMS 2.0, is more ambitious. Rajasthan plans to migrate the platform to a modern open-source technology stack and introduce AI and machine learning for transaction sampling, fraud pattern recognition and predictive analytics. Plans also include smart audit memos, automated balance sheet generation and an AI chatbot trained on historical audit data to support stakeholders.
The progression is significant. It marks the shift from asking whether auditing can be made digital, traceable and risk-based to asking whether accumulated audit data can make auditing more targeted and smarter.
That distinction goes to the heart of the Rajasthan experiment. It moves from recording an audit after the work is done to helping decide where to look, what to examine, how to track it and when to flag a risk.
Public audit is rarely seen as a frontline digital service. Yet its consequences directly affect the quality of public expenditure. When technology helps auditors track money more systematically, identify risks earlier and pursue compliance more visibly, digitisation becomes more than an administrative reform. It becomes an instrument of accountability.
"American roads are good not because America..
State Rankings Highlights -: Odisha scaled to number..
Step 1: Call for Project Submission Call for..
In the run-up to the elections, the most..

Inclusion is the first magazine dedicated to exploring issues at the intersection of development agendas and digital, financial and social inclusion. The magazine makes complex policy analyses accessible for a diverse audience of policymakers, administrators, civil society and academicians. Grassroots-focused, outcome-oriented analysis is the cornerstone of the work done at Inclusion.