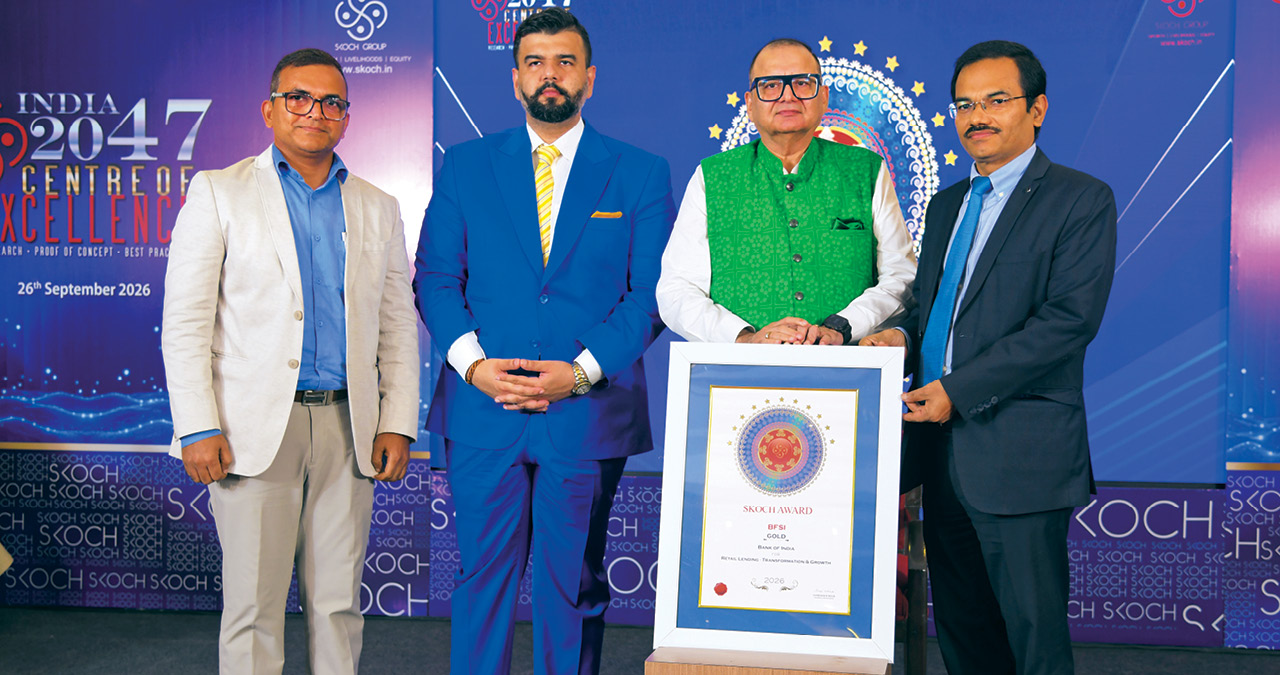
(L to R) Rohan Kochhar, SKOCH Development Foundation and Founder, SKOCH Law Offices; Sameer Kochhar, Chairman, SKOCH Group; Chandra Mohan Achary, Commissioner - ESD (MeeSeva), ITE&C Department, Government of Telangana; Umesh B, General Manager, Indian Overseas Bank
A newly opened bank account begins behaving unusually. Transactions pile up rapidly, money moves in and out at a pace that does not fit the ordinary pattern and the account crosses 500 transactions. Earlier, such an account depended on a manual escalation process; emails were sent only after the transaction count crossed 1,000. Today, at Indian Overseas Bank (IOB), a robotic process spots the threshold breach and automatically alerts the relevant branch.
The change appears simple. Its significance lies in what happened afterwards. Before the Robotic Process Automation (RPA) initiative, more than 150 accounts a day appeared on the list of accounts recording over 500 transactions. After implementation, IOB reports that this number fell to zero.
That dramatic movement captures a larger transformation taking place inside the bank. In two very different areas – preventing suspicious transactions and recovering stressed loans – IOB is attempting to replace processes that depend on human follow-up with systems that automatically identify, alert, record and escalate.
One operates at the beginning of the problem, trying to prevent an account from becoming part of a fraud chain. The other operates at the difficult end of banking, where a loan has already become a non-performing asset and recovery has entered a legally exacting process. Together, RPA and the Collection Recovery & Legal Management Software (CRLMS) offer a compelling picture of what digital transformation in banking can mean when it moves beyond customer-facing apps and into the less-visible machinery of risk, compliance and recovery.
IOB introduced RPA in its Anti-Money Laundering Department on 21 November 2025 to strengthen monitoring of newly opened accounts.
The earlier system included monitoring. Reports were generated for accounts opened in the preceding six months, later extended to nine months and captured accounts with 75 or more debit and credit transactions.
The weakness was what happened next. Communication with branches was manual and alerts were sent only when transactions exceeded 1,000. IOB changed both variables simultaneously: it automated communication and lowered the intervention threshold from 1,000 to 500 transactions. The RPA now extracts data, identifies accounts crossing the threshold and sends alerts to relevant branches.
This matters because suspicious money movement is partly a race against time. Automated alerts enable branches to investigate, contact customers and review accounts without waiting for the next manual monitoring cycle.
The process itself is simple: detect, alert, respond and act. RPA generates the monitoring report; data is classified and routed to the appropriate branch; the branch reviews the alert; and, following an investigation, action can be taken on the flagged account.
More importantly, the drop from over 150 accounts a day breaching the 500-transaction marker to zero suggests more than faster reporting. The alert appears to have changed behaviour at the branch and customer levels. IOB says the intervention sensitised customers to the risk of allowing their accounts to be used by fraudsters and reduced the number of accounts entering the monitoring list between December and March.
If RPA is about spotting trouble early, CRLMS deals with what happens when stress has already crystallised.Recovery under SARFAESI is highly procedural. A missed stage, delayed notice or documentation error can weaken the recovery process. IOB’s challenge was not merely to digitise documents but to transform a fragmented, paper-driven legal process into a controlled workflow.
Before CRLMS, the bank described legal recovery as characterised by paper-based processes, delayed approvals, fragmented tracking, limited real-time monitoring and a risk of procedural lapses. The new system replaces these with digital workflows, multi-level maker-checker approvals, automated compliance alerts, dashboards and an audit trail. CRLMS has been deployed across more than 3,500 branches, has over 10,000 active users and has processed more than 5,000 SARFAESI cases digitally. IOB reports a 60% improvement in legal recovery turnaround time.
The platform tracks the recovery journey through eight stages: NPA identification, Section 13(2) demand notice, borrower representation, Section 13(3A) reply, possession notice, asset valuation, sale notice and auction and finally recovery and closure. Each stage is digitally tracked and time-stamped.
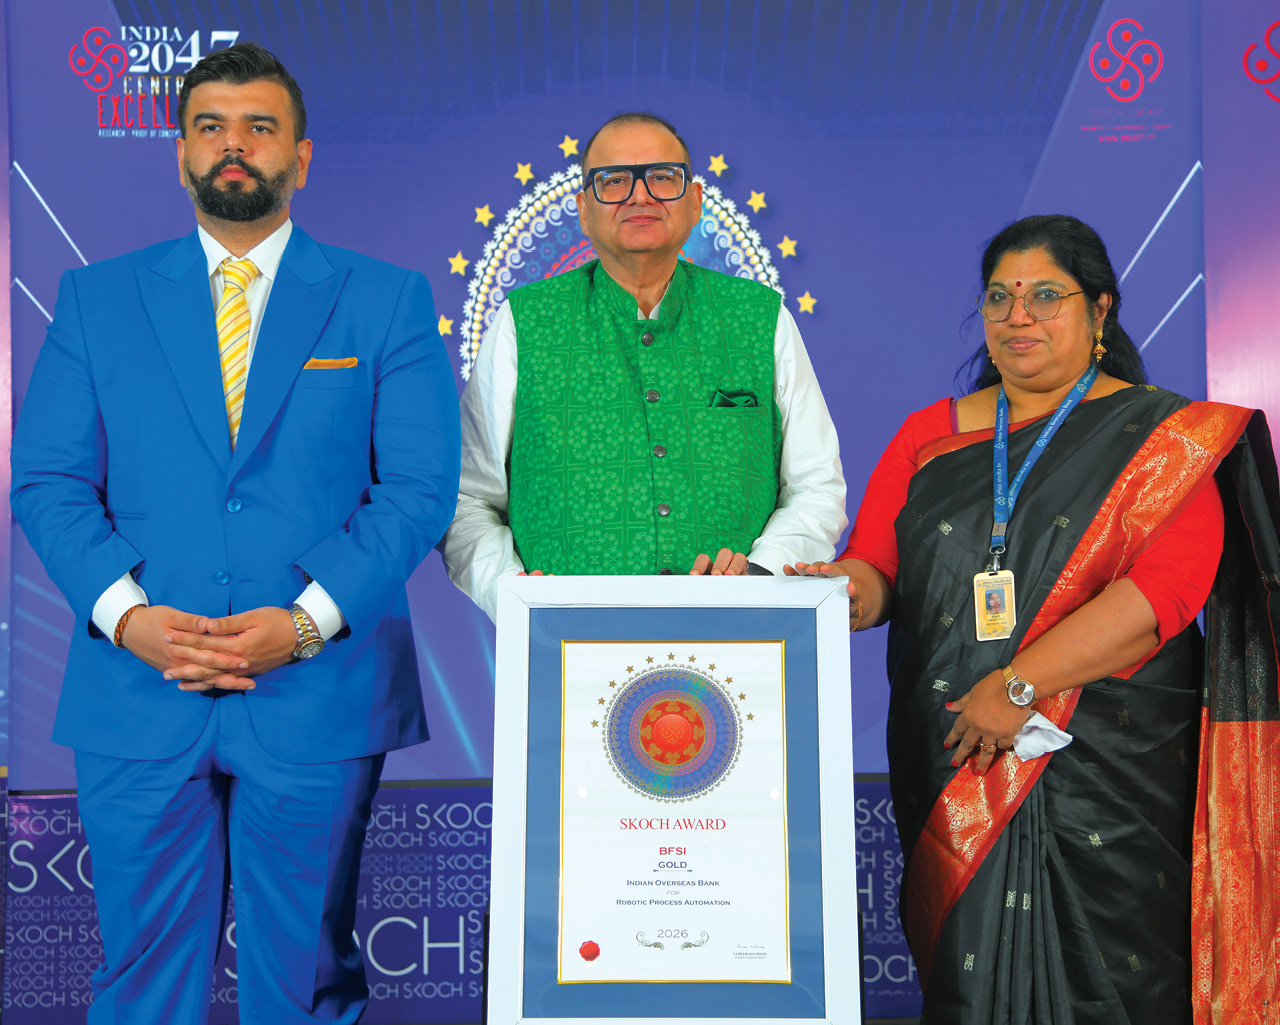
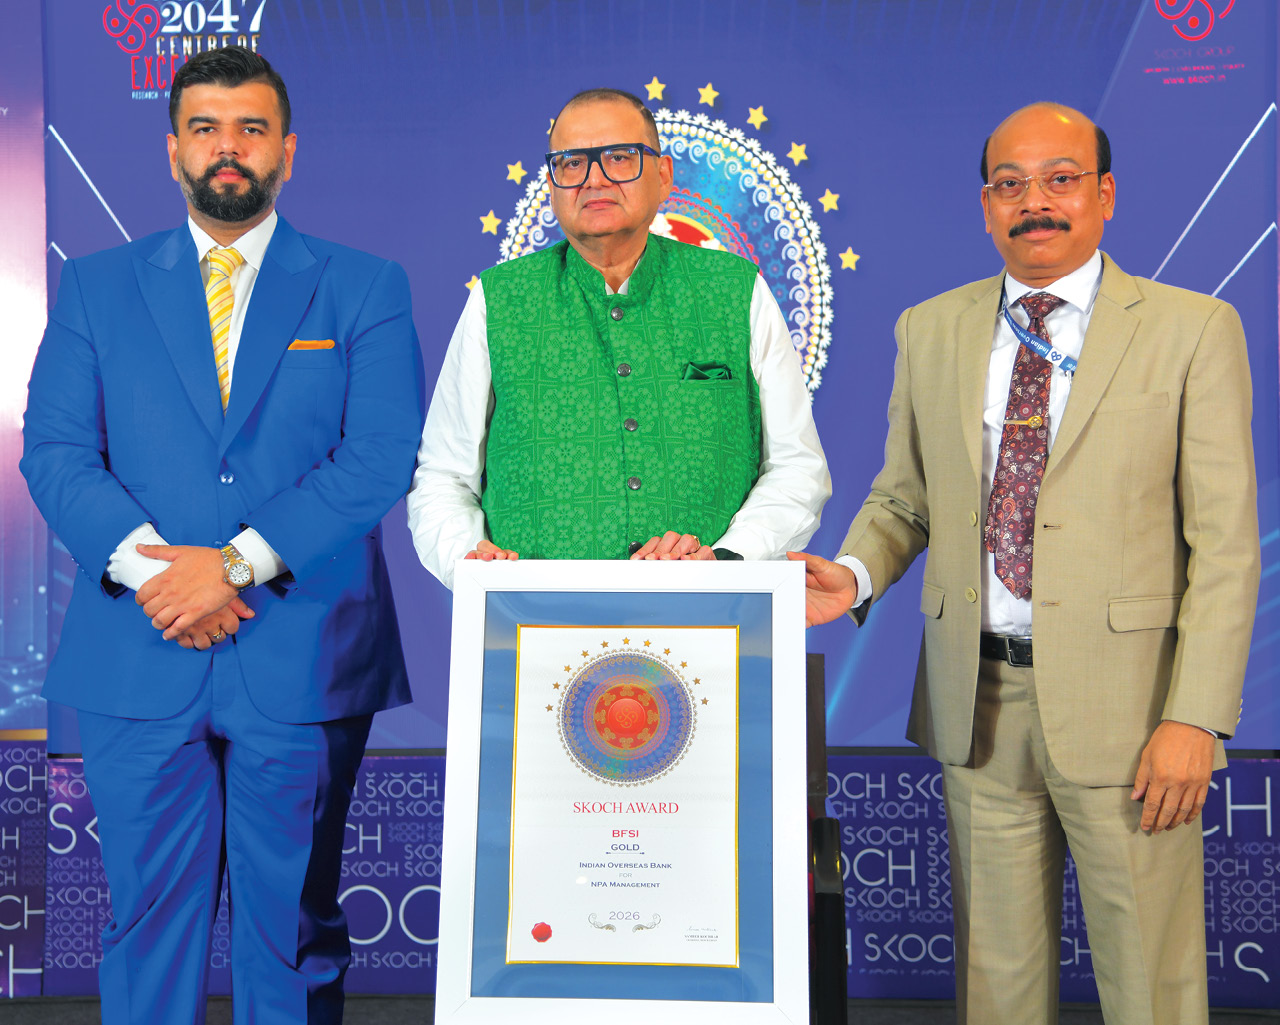
(L to R) Rohan Kochhar, SKOCH Development Foundation and Founder, SKOCH Law Offices; Sameer Kochhar, Chairman, SKOCH Group; K Sangeetha, Deputy General Manager, Indian Overseas Bank
IOB did not attempt the transition in one leap. The first SARFAESI component, covering action under Section 13(2), went live on 16 August 2023. Section 13(4) followed on 2 February 2024. The Lok Adalat module was introduced on 31 October 2024, the DRT module on 5 December 2024 and the Civil Suit module on 9 April 2025. Other components, including write-offs, OTS processing, NCLT processes covering CIRP and PIRP, Revenue Recovery and the ARC module, were reported to be under development or user acceptance testing.
IOB first studied the existing process, identified gaps, designed standardised workflows, piloted them with selected officers, incorporated user feedback and progressively rolled out the system. Training and change management accompanied implementation.
The challenge was as organisational as it was technological. Moving thousands of users from paper to digital workflows while keeping routine recovery work running required extensive training. Integration with existing banking systems had to work in near real time, while external users, including advocates and recovery agents, also needed to operate within the new environment.
IOB reports ₹301 crore recovered through the SARFAESI channel during FY2025-26, alongside a 71% reduction in gross NPAs and a 60% improvement in turnaround time. Care is needed in interpreting those figures: the documents do not establish that CRLMS alone caused the entire decline in gross NPAs. What they do establish is that the platform has transformed the infrastructure for managing recovery, standardising execution, accelerating processing, reducing manual effort and giving branches, regional offices and the central office a common view of proceedings.
RPA turns transaction velocity into an early warning and quickly delivers it to the branch. CRLMS turns legal recovery from a collection of files and follow-ups into an auditable sequence of actions. Neither system eliminates people. In fact, both depend on them.
"American roads are good not because America..
State Rankings Highlights -: Odisha scaled to number..
Step 1: Call for Project Submission Call for..
In the run-up to the elections, the most..

Inclusion is the first magazine dedicated to exploring issues at the intersection of development agendas and digital, financial and social inclusion. The magazine makes complex policy analyses accessible for a diverse audience of policymakers, administrators, civil society and academicians. Grassroots-focused, outcome-oriented analysis is the cornerstone of the work done at Inclusion.