India’s microfinance sector stands at a critical juncture. After substantially expanding formal credit to underserved households, particularly women, it must now make borrower outcomes the centre of its next phase. The challenge is to address over-indebtedness, repayment stress and rising credit costs through a responsible, technology-enabled, household-centric model that integrates financial inclusion with economic empowerment, customer protection and long-term resilience.
Where We Stand
Microfinance has significantly advanced financial inclusion by extending formal credit to underserved households, particularly women. As of 30 June 2026, the sector’s portfolio stood at approximately ₹3.28 lakh crore.
However, the recent cycle of over-leveraging, elevated early-bucket delinquencies and provisioning spikes has exposed vulnerabilities. While access has expanded, the sector must now evolve to sustain credit for borrowers and lenders alike.
An Evolving Model: JLGs Plus Technology
The Joint Liability Group (JLG) model has traditionally enabled rural outreach and mitigated lending risks. As the sector evolves, microfinance should increasingly adopt household-centric, cash-flow-based assessments.
Credit bureau information, consent-based financial data and improved household-level assessments can complement the JLG model. Group lending continues to provide valuable social and behavioural information, especially for first-time borrowers with limited financial histories.
For customers with established digital footprints, Account Aggregator data and cash-flow underwriting can reduce reliance on relationship-based assessments. The future lies in a hybrid model that combines technology-driven underwriting with local knowledge, personal relationships and stronger customer protection.
Guardrails: Industry and Regulator Together
Responsible microfinance requires industry-led safeguards and regulatory oversight. Together, they instil the discipline needed for sustainable lending. Industry standards, such as the three-lender cap per borrower and the ₹2 lakh indebtedness limit, can help prevent excessive borrowing. However, regulatory minimum standards remain essential to ensure financial stability and consumer protection.
The RBI’s microfinance framework mandates household-level assessments of income and indebtedness and caps monthly repayment obligations at 50% of household income. A principles-based regulatory framework, reinforced by industry standards and effective monitoring, can provide the necessary balance between financial access and lending discipline.
Seeing the Full Picture: Credit Bureaus
Borrowers may access credit simultaneously from MFIs, banks, self-help groups and fintech platforms. In this context, individual lenders may underestimate total indebtedness without comprehensive information.
Credit bureaus are therefore essential to responsible lending. Their information must be timely, accurate and comprehensive, with adequate safeguards for consent, privacy and data security. However, bureau information alone cannot establish repayment capacity. To complete the picture, lenders must also assess household income, cash flows and borrowing requirements. Combining bureau records with consent-based Account Aggregator data and social payment behaviour can enable more informed lending decisions.
Recovery: Protection and Credit Flow
Effective recovery and borrower protection must reinforce each other, not compete. The recovery framework should be integrated into the broader lending discipline.
The RBI’s recovery framework prohibits harsh and coercive practices while permitting legitimate recovery. Clear communication, grievance redressal and transparent lending terms are essential to maintaining borrower confidence. Excessively restrictive recovery conditions can also discourage lending, ultimately affecting responsible borrowers.
The sector must therefore emphasise stronger underwriting, early identification of repayment stress and humane yet effective recovery practices. Responsible recovery protects both the borrower and the continuity of credit.
Beyond Credit: Empowerment and Resilience
The success of microfinance should no longer be measured solely by the number of loans extended to women. More meaningful indicators include productive activity, income generation, asset creation and greater participation by women in financial decision-making. Borrower outcomes must become the primary measure of progress.
Credit alone cannot provide financial security. Insurance, pensions, savings and payments must be part of an integrated offering. Schemes such as PMJJBY, PMSBY and Atal Pension Yojana can help protect vulnerable households against unforeseen shocks and old-age insecurity.
The priority is not to multiply financial products but to ensure they are affordable, suitable, understandable and regularly used. SHGs, banks and other last-mile institutions can facilitate access and strengthen financial literacy. The objective must shift from financial access to financial security and resilience, with borrower outcomes at the centre.
SHGs and MFIs: Complementary Channels
Self-help groups and microfinance institutions often operate in the same communities. Rather than viewing them solely as competitors, the sector should recognise how their strengths complement one another.
SHGs provide savings discipline, community networks and social capital. MFIs contribute specialised credit delivery, operational scale and last-mile outreach. The SHG-bank linkage programme already has considerable reach, with 92 lakh women’s SHGs under DAY-NRLM as of July 2026. Greater interoperability and customer choice can help borrowers progress from small group-based loans to larger formal enterprise finance as their repayment capacity and economic activity grow.
Innovation and Fintech
Digital lending offers opportunities to reduce operating costs, improve underwriting and extend financial access. At the same time, predatory lending applications have highlighted risks for vulnerable borrowers.
Innovation should be encouraged where it improves affordability, access and credit assessment, but customer protection must remain paramount. Regulated lenders must retain responsibility for the entire customer journey, including sourcing, underwriting, pricing, data use and recovery. Technology partnerships cannot be used to outsource regulatory accountability.
Action Plan for the Next Two Years
Two priorities should guide the sector over the next two years: creating a structured graduation pathway for borrowers and substantially reducing the cost of credit. Together, they set the sector’s immediate direction. Both should be judged by their impact on borrower outcomes.
Instead of repeatedly extending similar small-ticket loans, lenders should use repayment histories, bureau data and consent-based cash-flow data to identify borrowers eligible for larger, productive loans.
This enables customers to progress economically rather than remain dependent on successive borrowing cycles. Reducing lending rates requires attention to three cost components: borrowing, operational and credit costs. A more resilient microfinance ecosystem can lower borrowing costs. Technology-enabled last-mile delivery can improve operational efficiency, while stronger underwriting and digital collections can reduce credit costs.
These measures can improve affordability for borrowers and enhance sustainability for institutions.
Looking at the Next Five Years
Over the next five years, microfinance is likely to become increasingly digital, data-driven and integrated with mainstream financial services. Even so, specialised institutions will remain important for reaching underserved households.
Digital infrastructure can reduce transaction costs, improve underwriting and make credit more accessible. Yet technology cannot entirely replace trust, financial literacy, local knowledge and personal assistance, particularly for first-time and vulnerable borrowers.
The future should not be framed as a choice between fully digital mainstream banking and specialised standalone institutions. Both have complementary roles. Microfinance must ultimately evolve from a standalone credit product into an integrated financial services ecosystem, with technology providing the infrastructure and specialised institutions sustaining the last-mile relationship.
Its long-term success will depend not merely on expanding credit, but on enabling households to achieve greater economic capacity, financial security and resilience. To do this, the sector should adopt a sharper policy roadmap and place borrower outcomes at the centre of its next phase. That is the central test for the sector.
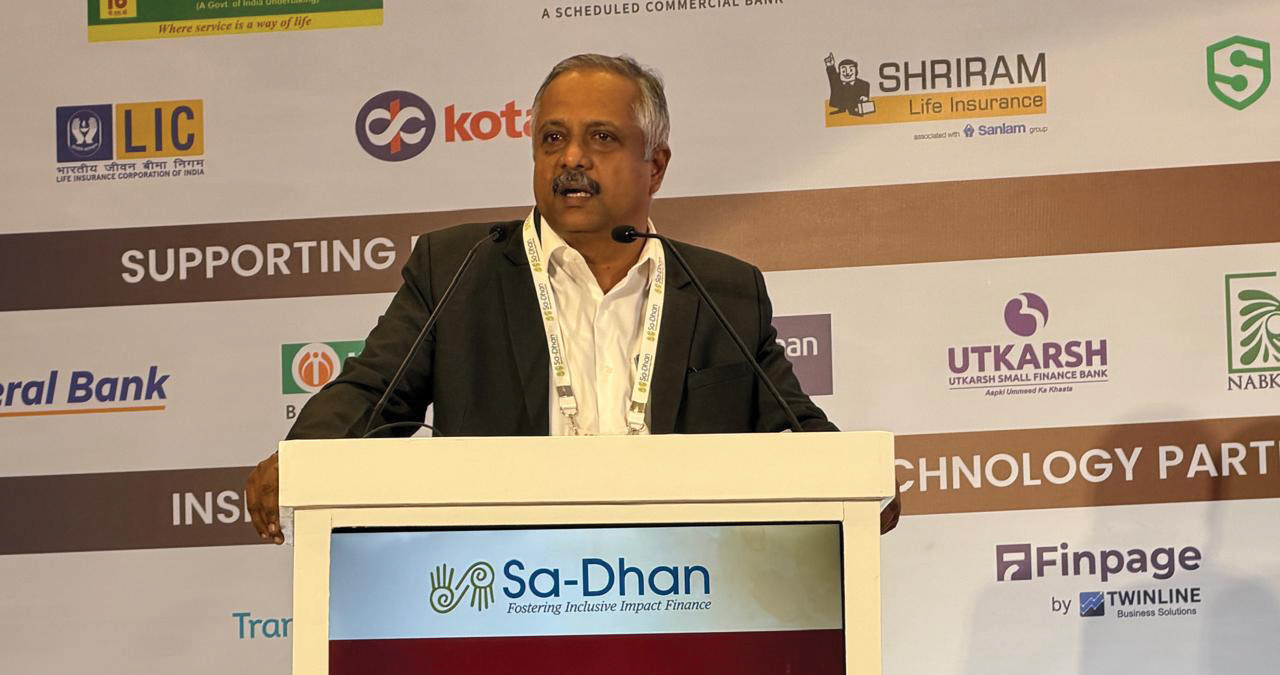
Based on his address at 21st Sa-Dhan National Conference on Inclusive Growth – Microfinance: Resilient Growth for Responsible Lending, New Delhi
India intends to become a USD 30 trillion economy by 2047. Reaching that mark from a base of roughly USD 3.96 trillion implies sustained nominal growth near 9.6 percent in...
There are three goals for 2047. One is to become a developed nation, second is inclusiveness in terms of employment, human development to everyone so that inequalities can be reduced....
"American roads are good not because America..
State Rankings Highlights -: Odisha scaled to number..
Step 1: Call for Project Submission Call for..
In the run-up to the elections, the most..

Inclusion is the first magazine dedicated to exploring issues at the intersection of development agendas and digital, financial and social inclusion. The magazine makes complex policy analyses accessible for a diverse audience of policymakers, administrators, civil society and academicians. Grassroots-focused, outcome-oriented analysis is the cornerstone of the work done at Inclusion.